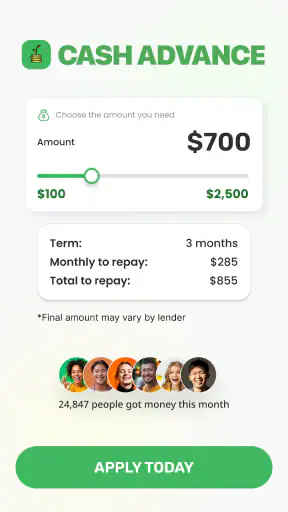
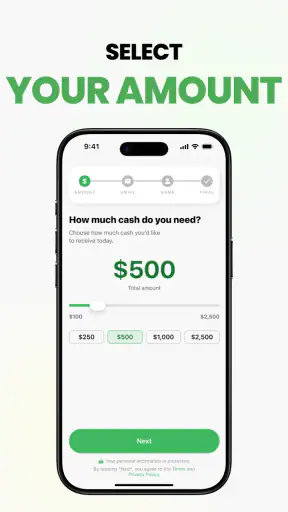
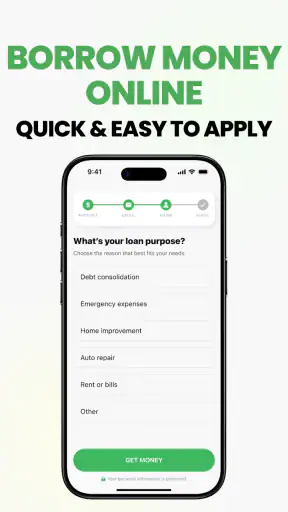
When an unexpected bill lands between paydays, a cash advance app can feel more practical than searching through several lenders or waiting for a traditional application. I looked at Instant Cash Advance Loan App as a finance tool for that exact kind of short-term pressure. My impression is mixed in a useful way: it is easy to understand at a glance and free to install, but borrowing money through any app requires more care than downloading an ordinary budgeting tool.
The app is developed by Fast Online Loans and focuses on arranging a quick cash advance rather than managing investments, tracking spending, or building a long-term financial plan. That narrow purpose matters. I would consider it when I needed to explore a short-term borrowing option, not as the main place to organize a household budget. Its store presence is substantial, with an average rating of 4.6 from around 52 thousand ratings and more than a million installs. Those figures suggest that many people have tried it, although popularity should never replace checking the actual terms shown during an application.
How it fits into a shared household
A realistic shared-device situation
Imagine a couple using the same tablet at home. One person notices that a utility payment is due before the next salary arrives and opens the app to investigate a cash advance. The other person may later use the same device for a completely different task. That sounds simple, but finance apps are not like games or recipe apps: an open session, saved form, notification, or browser history can reveal sensitive information.
My first practical recommendation is to treat the app as a personal financial workspace even when the phone or tablet is shared. I would open it only when the intended borrower is present, avoid leaving an application screen unattended, and close the session before handing the device to someone else. I would also avoid entering another household member’s details casually. If an application asks for information about a co-borrower or another person, that person should understand what is being submitted and why.
This is one of the app’s most important real-world limitations: the convenience of a shared device can blur personal boundaries. The application itself should not be mistaken for a household account. I would not use one person’s profile as a general family borrowing profile, and I would not assume that two adults using the same device can safely share login details or application history.
What I would do before opening an application
I would begin by writing down the exact amount needed and the date when repayment could realistically happen. That small step prevents the app from becoming a place where I borrow first and calculate later. A cash advance may solve a timing problem, but it does not remove the underlying expense. If the repayment date depends on uncertain overtime, a delayed benefit, or money another person merely promised to send, I would pause before proceeding.
I would also compare the app with familiar alternatives. A bank overdraft, a credit-union option, an employer advance, or negotiating a payment date with the bill provider may be less expensive or easier to understand. The right comparison is not only the amount received. I would look at the total repayment, any fees, the due date, consequences of being late, and whether the arrangement could cause another shortfall next month.
The most useful habit is to decide the repayment plan before treating the application as a solution. That advice is particularly important in a household, where one person may assume another person will cover the balance. Clear agreement is safer than relying on an informal promise made during a stressful evening.
Keeping account boundaries clear
The app is free to download, but that does not mean borrowing through it is free. The installation price and the financial cost of a loan are separate questions. I would read every offer and disclosure presented in the process rather than assuming that the word “free” applies to the advance itself. If the figures are difficult to locate or the repayment schedule is unclear, I would stop and compare another option.
On a shared device, I would keep personal email, phone verification, bank information, and identification details tied to the actual applicant. I would not let another household member complete a form simply because they are more comfortable with mobile apps. That can create mistakes in names, addresses, income information, or repayment details, and it makes later clarification harder.
I would also avoid saving screenshots of sensitive pages in a shared photo library. A screenshot can be useful for personal records, but on a family tablet it may become visible to anyone browsing images. A private note or secure document is a better place to record the amount, due date, and contact information connected with the application.
Coordinating without turning borrowing into a surprise
When money is shared, the decision should be shared at the level that matters. I would tell the other adult responsible for household bills how much I planned to borrow, what expense it covered, and how the repayment would fit into the next budget. This is not about asking permission for every personal decision; it is about preventing a repayment from colliding with rent, groceries, utilities, or another scheduled payment.
A simple written plan can help. I would record the intended amount, the expected repayment date, and which income source will cover it. If the app presents a different amount or schedule than expected, I would update that plan before accepting anything. This is a concrete advantage of slowing down: a household can spot a problem while it is still a choice rather than after the money has been spent.
I would not use the app as a coordination tool for several people borrowing separately. A household can quickly lose track of overlapping obligations when each person applies from their own phone. If more than one person is considering an advance, I would compare the combined repayment burden against the next month’s essential expenses. Two manageable-looking advances can become one unmanageable household problem.
Another useful workflow is to separate urgent needs from optional spending before applying. If the request is for food, transport to work, or a time-sensitive bill, the decision deserves a different conversation from a purchase that can wait. The app may make both actions feel equally immediate, but the household consequences are very different.
What the app is, and what it is not
I see this product as a focused borrowing gateway, not a full financial coach. Its store summary presents it as a way to seek a fast cash advance, and that is the lens through which I would judge it. I would not expect it to replace a spreadsheet, a banking app, a debt counselor, or a shared budgeting system. Those tools answer different questions: where money is going, how much is available, and how to reduce future pressure.
Compared with visiting a lender in person, an app can feel more private and convenient because the first steps happen on a phone. Compared with a bank’s established borrowing service, however, a dedicated loan app may require more independent checking of terms and provider details. Compared with asking a friend or relative for help, it avoids a personal debt conversation but creates a formal repayment obligation. None of these choices is automatically best; the right option depends on cost, timing, privacy, and the borrower’s ability to repay.
That comparison is especially important for a shared household. A bank account app may already show the family’s real cash flow, while this app is designed around obtaining an advance. If I were trying to understand why the household is repeatedly short before payday, I would start with transaction history and a budget rather than repeatedly opening a loan application.
Age, trust, and responsible access
The app carries an Everyone content rating, which describes the store’s content classification rather than proving that every person is eligible to borrow. Financial products involve adult decisions, identity details, and repayment responsibilities. I would keep the app away from children’s casual use and would not let a child experiment with an application form on a parent’s device.
In a household with teenagers, I would explain that seeing a finance app does not mean they can use it. I would also make sure notifications or previews do not expose financial information on a lock screen visible to visitors or other family members. The practical issue is not only trust between relatives; it is also the risk of someone tapping through a process without understanding the consequences.
Trust should work both ways. If another adult asks to borrow the device, I would close the app first. If someone says they have already applied, I would ask to see the repayment plan rather than relying on a vague description. These are ordinary boundaries, but they matter more when the app deals with identity and money.
I would also be cautious about pressure. A fast application can encourage an emotional decision when a bill feels urgent. I would take a short break after reviewing the offer and ask whether the household can still meet essential costs after repayment. If the answer is no, speed is not the feature I need; a different solution is.
Version, availability, and everyday usability
The current version is 2.0.9 and it supports Android 7.0 or later. That makes it relevant to people keeping an older Android phone in service, including a spare household device. I would still avoid installing a finance app on a phone that no longer receives security updates or is routinely passed between many people. Compatibility makes installation possible; it does not automatically make the device a good place for sensitive financial activity.
Because the app is free and has attracted more than a million installs, it is easy to see why someone might choose it for a quick first step. I would treat those signals as reasons to investigate, not as a guarantee that an offer will suit my circumstances. The rating and review volume can indicate that the app is familiar to many users, but they cannot tell me whether the repayment terms are affordable for my household.
One non-obvious point is that a spare phone can create false confidence. A device used only for finance may seem safer, but if its operating system, screen lock, or account access is neglected, it may be less protected than the main phone. I would choose the better-secured device, not simply the least-used one.
Where the experience may become uncomfortable
The main friction is not necessarily tapping through the app; it is understanding what happens after the initial request. A borrower needs to distinguish between an eligibility check, an application, an approval, and money actually arriving. I would read each screen carefully and avoid assuming that an early indication means the final funds are guaranteed.
I would also watch for the emotional effect of a short route to borrowing. If the process feels smooth, it can hide the fact that repayment is still a fixed obligation. This is why I would not apply while distracted, tired, or discussing several household emergencies at once. I would prepare the necessary figures beforehand and review the final terms with a clear head.
Another limitation is suitability. Someone with irregular income, existing high-cost debt, or no realistic repayment date may need advice and a broader debt plan rather than another short-term advance. Someone who only needs a few days of flexibility may find that changing a bill date or using an existing low-cost facility is better. The app is most useful when the need is genuinely temporary and the repayment source is dependable.
My household verdict
After looking at it as both a finance app and a shared-device responsibility, I would recommend Instant Cash Advance Loan App only as a starting point for carefully comparing a short-term borrowing option. I like its focused purpose, free installation, broad availability on supported Android devices, and straightforward appeal to someone facing a temporary cash gap. I would not recommend opening it casually, sharing an account, or treating a fast application as a substitute for a household budget.
The best use case is a financially organized adult who knows the exact amount needed, has a dependable repayment date, and is willing to compare the complete cost with alternatives. The weakest use case is a household already borrowing to cover earlier borrowing, or one where people are not communicating about shared bills. In that situation, a bank adviser, credit union, bill negotiation, or debt-support service may be more appropriate than another advance.
My final advice is practical: use a personal device or a carefully secured shared one, keep each applicant’s information separate, record the repayment obligation, and discuss the effect on household cash flow before accepting anything. The app can make the first step convenient, but the quality of the decision still comes from the borrower. For me, that makes it a potentially useful emergency option, not an automatic answer to financial stress.


